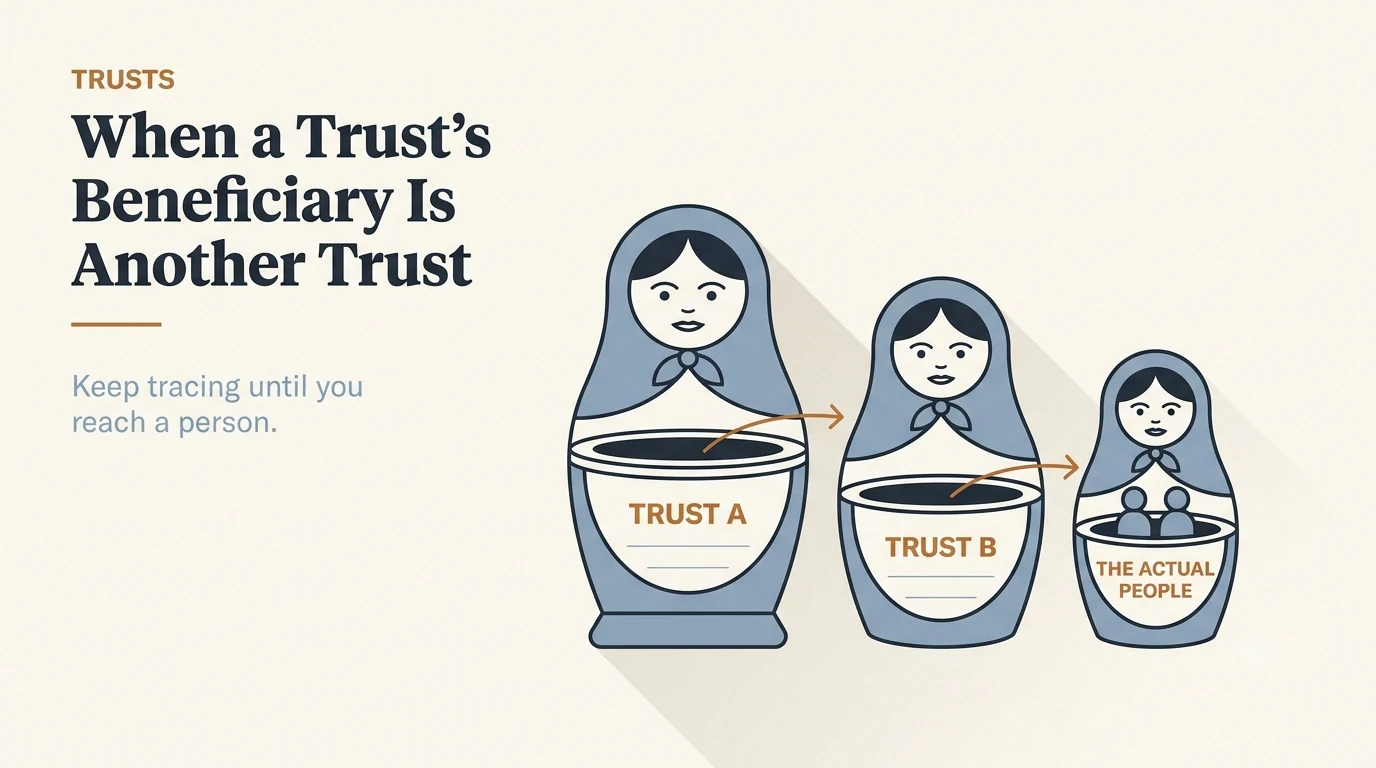
A trust named by another trust does not necessarily end the beneficiary analysis
The final RMD regulations contain rules for identifying beneficiaries of a see-through trust when another trust appears in the beneficiary chain. The analysis can require looking through the second trust to the individuals or entities who can ultimately receive the retirement-plan interest.
Why this happens
An accumulation trust may retain IRA distributions and later distribute trust property to remainder beneficiaries. If a remainder beneficiary is itself another trust, the first trust document alone may not reveal whether the ultimate recipient is an individual, charity, estate, or another entity. That distinction can affect whether there is a designated beneficiary and whether an eligible designated beneficiary exception is available.
Example: Trust A → Trust B → grandchildren
Suppose an IRA is payable to Trust A. Trust A can accumulate IRA withdrawals and, at the primary beneficiary’s death, distribute remaining property to Trust B. Trust B is solely for two grandchildren. A proper RMD review may need both trust instruments and any amendments to determine which beneficiaries count under the regulatory look-through rules.
Do not rely on account registration to answer the trust question
The IRA statement may show only “Trust A, beneficiary.” It will not explain the distribution powers, contingent interests, or whether another trust is part of the chain. The tax analysis is document-driven.
Build a beneficiary tree, not a paragraph summary
- Start with every person or entity that can receive retirement-account amounts from Trust A.
- For any beneficiary that is another trust, identify who can receive from that trust.
- Mark charities, estates, and other non-individual recipients separately.
- Identify any individual who may qualify as an eligible designated beneficiary.
- Confirm the documentation package includes the instruments needed to prove the chain.
The 2024 regulations limited how far the look-through reaches
The final regulations narrowed the search for accumulation trusts: certain beneficiaries who could take only after the death of another beneficiary—sometimes called mere potential successors—can be disregarded, and the analysis focuses on the beneficiaries who can actually receive the retirement interest. But the specific cutoff depends on the trust type and how the tiers are structured. A conduit trust, an accumulation trust, and a trust divided immediately at death are not analyzed the same way, so the rule that applies has to be matched to the actual document.
A lower-tier trust for an EDB usually does not import the EDB exception
If Trust B benefits a disabled grandchild, that does not by itself give the arrangement eligible-designated-beneficiary treatment. The EDB generally has to be a beneficiary of the trust named directly on the IRA and the structure has to meet the applicable multi-beneficiary-trust conditions. Discovering an EDB two trusts down the chain is a reason to get specialized advice, not an automatic life-expectancy result.
Why professional review is often justified
Nested trusts combine tax regulations with state-law trust interpretation. A custodian can process beneficiary paperwork but may not determine which remote trust beneficiaries count under the final regulations. The practical role of this checklist is to surface the documents and questions before a deadline is missed—not to replace trust counsel.
Nested trusts make documentation deadlines harder
If Trust A names Trust B, the plan administrator may need enough documentation to identify the beneficiaries through both instruments. Waiting until the deadline to discover that an amendment or second trust document is missing can jeopardize see-through treatment.
Use a terminal-beneficiary test
For each branch, keep tracing until you reach a person or entity that can actually receive the retirement-plan interest without another trust layer. Mark whether that terminal recipient is an individual, an EDB, a charity, an estate, or another non-individual. The beneficiary tree then shows why each branch matters.
Trust mergers and decanting after death need specialized review
Changes to trust structure after the IRA owner’s death can affect which document controls and which beneficiaries are taken into account. Do not assume a post-death trust reorganization automatically preserves the original RMD treatment; coordinate trust counsel and tax counsel before changing the chain.
Do not stop tracing because the second trust has the same trustee
The identity of the trustee is not the beneficiary test. The same bank or family member can serve as trustee of both trusts while the beneficial interests differ completely. RMD classification follows the people and entities entitled to the retirement benefit under the governing instruments, not who signs the custodian paperwork.
| RMD question | Trustee | Beneficiary |
|---|---|---|
| What the name shows | Who signs or administers paperwork | Who can ultimately receive the retirement interest |
| Why matching names can mislead | The same bank or person may serve both trusts | The beneficial interests can still differ completely |
| What to trace | Custodian and trust administration records | People and entities entitled under the trust instruments |